 Australia
 USA
 Canada
 UK
 Ireland

Month-end close delays often start with missing client documents, unfinished reconciliations, manual bookkeeping and limited staff capacity. Australian CPA firms and accounting practices can reduce these delays by standardising close checklists, spreading routine work throughout the month, setting clear client deadlines and delegating repeatable accounting tasks to a trained outsourced team under appropriate firm supervision.
The objective is not simply to finish the books faster. It is to deliver reliable management accounts, prepare BAS information on time, resolve discrepancies earlier and give internal accountants more capacity for review and advisory work.
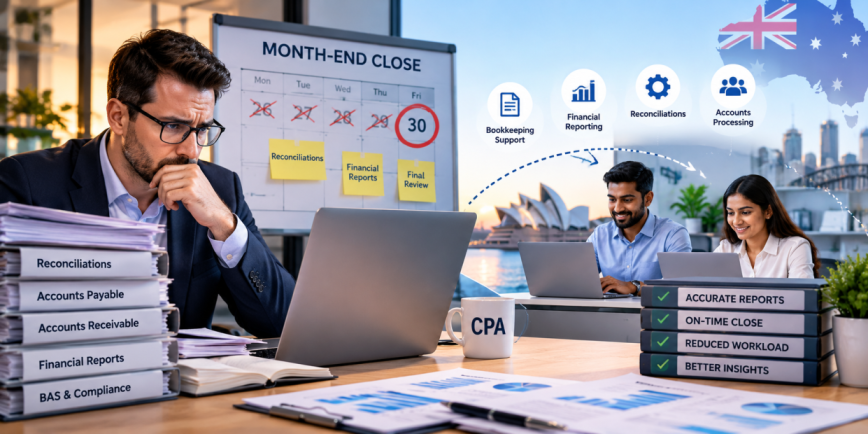
Five Steps to Reduce Month-End Close Delays
- Identify the bottlenecks: Review the last three monthly closes to find recurring delays, missing documents and avoidable rework.
- Standardise the workflow: Use one close calendar with named task owners, due dates and clear completion criteria.
- Move routine work earlier: Reconcile accounts weekly, prepare recurring schedules and collect client documents before month-end.
- Delegate repeatable tasks: Use outsourced accounting support for agreed bookkeeping, reconciliations and draft workpapers, while the firm retains professional review and decision-making.
- Measure the results: Track days to close, reconciliations completed by the target date, late client documents and rework hours.
Before sharing client information with an outsourced provider, establish appropriate client permissions, confidentiality arrangements, access controls and supervision procedures.
Why Do Month-End Close Delays Happen in Australian Accounting Firms?
Month-end close involves more than entering transactions and preparing financial statements. Accounting practices must reconcile accounts, investigate discrepancies, collect supporting documents and review financial information before issuing reports.
Five recurring bottlenecks deserve particular attention.
1. Missing Client Documents
Late bank statements, invoices, receipts, payroll records and loan statements prevent accountants from completing reconciliations and confirming balances.
How to address it: Set a document submission deadline for every client, send reminders before close begins and maintain a single list of outstanding information.
2. Manual Data Entry and Reconciliation
Repeated transaction coding, manual matching and spreadsheet-based reconciliations consume time that could be spent reviewing results or advising clients.
How to address it: Use suitable accounting software automation and delegate repeatable processing tasks to trained staff following documented procedures.
3. Unclear Task Ownership
A reconciliation can remain unfinished when the preparer, reviewer and client contact are unclear about who must complete the next action.
How to address it: Assign one accountable owner to each task, identify the reviewer and record the next action and deadline.
4. Inconsistent Accounting Procedures
Different approaches to expense coding, accruals, prepayments and supporting documentation increase review time, particularly when several team members work on the same portfolio.
How to address it: Create reusable procedures and client-specific checklists so workpapers arrive in a consistent format.
5. Competing BAS, Payroll and Reporting Deadlines
Australian accounting practices must coordinate monthly management accounts with BAS preparation, payroll reconciliations, superannuation obligations and financial year-end work. Quarter-end reporting can place additional pressure on teams already handling monthly client work.
How to address it: Maintain an Australian compliance calendar and complete suitable reconciliations and supporting schedules throughout the month rather than waiting until the reporting deadline approaches.
What Is Outsourced Accounting Support?
Outsourced accounting support involves delegating agreed bookkeeping and accounting activities to an external service provider while the accounting practice retains responsibility for its client relationships, review arrangements and professional obligations.
Depending on the agreed scope, an outsourced team may assist with:
- Transaction processing, categorisation and bookkeeping.
- Bank, credit card and balance sheet reconciliations.
- Accounts payable and accounts receivable processing.
- Expense coding and supporting-document checks.
- Accrual and prepayment schedules.
- Fixed asset register maintenance.
- Intercompany reconciliations and supporting schedules.
- Draft management reports and month-end workpapers.
- Missing-document lists and reconciliation exception reports.
For practices using a white-label model, the outsourced team works within the firm’s established processes and reporting formats. The practice manages the client relationship, determines accounting treatments that require professional judgement, reviews deliverables and retains the responsibilities applicable to its engagement.
A clear division of work helps avoid duplicated effort: the outsourced team prepares agreed deliverables, and the firm’s designated personnel review and approve them.
How Can Outsourced Accounting Support Reduce Month-End Close Delays?
1. Identify the Bottlenecks Before Outsourcing
Review the last three month-end closes before deciding which work to delegate. Record when each task was due, when it was completed and what caused any delay.
A bottleneck register can include:
| Information to record | Example |
| Delayed task | Balance sheet reconciliation |
| Main cause | Missing loan statement |
| Time lost | Hours spent waiting and following up |
| Responsible party | Client contact or assigned preparer |
| Proposed improvement | Earlier document request and escalation |
| Outsourcing opportunity | Prepare the reconciliation once the statement arrives |
The example above is illustrative, not a reported Aone client result.
This analysis distinguishes work that is suitable for outsourcing from delays caused by unavailable client information, unresolved accounting decisions or late approvals. Outsourcing can improve processing capacity, but it cannot eliminate dependencies that remain outside the provider’s control.
2. Introduce a Standard Close Calendar and Checklist
A standard checklist makes responsibilities visible and reduces the time spent asking what needs to happen next.
The following is an illustrative timetable for a straightforward monthly engagement with timely source documents.
| Task | Primary owner | Illustrative target |
| Collect documents and identify missing items | Client contact and account manager | Before close |
| Import and categorise transactions | Assigned preparer | Business days 1–2 |
| Reconcile bank and credit card accounts | Outsourced preparer | Business days 2–3 |
| Review accounts payable and receivable | Assigned preparer | Business days 2–4 |
| Prepare accruals and prepayment schedules | Agreed preparer | Business days 3–4 |
| Complete balance sheet reconciliations | Assigned preparer | Business days 3–5 |
| Investigate exceptions and missing evidence | Preparer and client contact | Business days 4–6 |
| Review draft management accounts | Internal reviewer | Business days 5–7 |
| Resolve review notes and issue approved reports | Assigned team and reviewer | Target business days 7–8 |
These are planning targets, not statutory deadlines or universal industry benchmarks. Complex engagements may require longer.
Every task should have a due date, an owner, a completion status and supporting evidence where appropriate. The same checklist should be accessible to authorised internal and outsourced team members.
3. Move From a Month-End Rush to a Continuous Close
A continuous, or soft-close, approach spreads suitable accounting activities throughout the month. Instead of leaving most reconciliations until the reporting period ends, the team resolves routine items as transactions occur.
For example:
- Weekly: Reconcile bank feeds, review uncategorised transactions and investigate unusual balances.
- During the month: Process supplier invoices, customer receipts and recurring transactions.
- Before month-end: Request missing statements, confirm payroll information and review recurring journals.
- Immediately after month-end: Complete final reconciliations, review adjustments and prepare draft management reports.
An outsourced team can complete agreed processing tasks during the month and flag exceptions before they become close-critical. Internal accountants then have more time to investigate unusual transactions and review financial results.
This approach is particularly useful for practices managing multiple bookkeeping, management accounting and BAS engagements simultaneously.
4. Delegate Repeatable Processing Tasks
Senior accountants should not need to complete every routine reconciliation or transaction-processing task themselves.
Consider a client whose bank reconciliation contains several unmatched transactions. The outsourced preparer can match supported transactions, attach evidence, identify outstanding items and prepare a reconciliation workpaper. The internal accountant can investigate material discrepancies, decide how unusual transactions should be treated and review the completed work.
Begin with tasks that have clear instructions, predictable inputs and objective completion criteria. Expand the scope only when turnaround times and workpaper quality meet the firm’s requirements.
5. Use Accounting Software and Automation Effectively
Platforms such as Xero, MYOB and QuickBooks Online offer features that can reduce manual processing when configured appropriately.
Useful measures include:
- Configure rules for recurring transactions that are well understood.
- Use consistent account codes and tracking categories.
- Set up appropriate recurring journals.
- Integrate document capture with the bookkeeping process.
- Review exception reports for unmatched or unusual transactions.
- Periodically validate automated coding rules.
Automation should not replace review. An incorrect bank rule can repeatedly misclassify transactions, while an automated match does not necessarily establish that a transaction has been accounted for correctly.
The strongest workflow combines suitable automation, trained processing staff and internal review.
6. Establish Client Document Deadlines and a Query Process
Client communication should follow a predictable timetable rather than relying on repeated individual emails.
| Timing | Action |
| Before month-end | Request expected statements, invoices, payroll records and other supporting information. |
| Close day 1 | Send one consolidated list of missing documents. |
| Close day 3 | Escalate outstanding items that threaten the close deadline. |
| Close day 5 | Confirm unresolved issues and their impact on reporting. |
| Before finalisation | Obtain necessary explanations, decisions and approvals. |
The outsourced team can prepare missing-document lists and handle routine follow-ups within the agreed communication process. The firm’s client relationship owner should handle sensitive discussions, disputed matters and issues requiring professional advice.
7. Define Responsibilities and Manage Offshore Handoffs
When work is shared between an Australian practice and an offshore accounting team, a clear handover process is essential.
| Activity | Outsourced team | Australian practice | Client |
| Routine transaction processing | Prepares | Oversees as agreed | Supplies records |
| Bank reconciliations | Prepares and flags exceptions | Reviews and resolves material issues | Explains missing or unclear transactions |
| Accounting adjustments requiring judgement | Provides supporting schedules | Determines and approves treatment | Supplies relevant information |
| Draft management reports | Prepares agreed drafts | Reviews and authorises release | Receives approved reports |
| Outstanding-document follow-up | Prepares requests or follows agreed procedures | Owns escalations | Provides documents |
This is a practical responsibility model, not a substitute for a formal engagement-specific RACI or professional responsibility assessment.
For offshore teams, agree on working-hour overlap, handover cut-off times, escalation contacts and expected response times. For example, a query arriving at 4 pm Australian Eastern Standard Time should have a defined next step: urgent items go to the nominated Australian contact, while routine items enter the next agreed handover queue.
The arrangement should also specify how work is transferred securely, how status is recorded and what happens when a deadline is at risk. Do not assume that an offshore team will always be available during Australian business hours.
What Australian Compliance Deadlines Should Your Month-End Calendar Include?
Month-end accounting does not operate in isolation. BAS, payroll, superannuation and year-end requirements affect how firms schedule their work.
| Deadline or event | Why it matters | Workflow to plan |
| 21st of the following month | Monthly BAS lodgement and payment are generally due on this date, subject to applicable arrangements. | Prepare reconciled GST data and investigate exceptions early. |
| 28th of the month after quarter-end | Standard quarterly BAS deadlines are generally 28 October, 28 February, 28 April and 28 July. | Complete a pre-close before quarter-end and leave time for review. |
| Each payday | Payday Super commenced on 1 July 2026. Employers generally need to ensure contributions reach employees’ funds within seven business days after payday, subject to applicable rules and exceptions. | Reconcile payroll and superannuation regularly rather than leaving discrepancies until month-end. |
| 14 July | The standard STP finalisation date for many employers. Different rules may apply in particular circumstances. | Include payroll reconciliation and finalisation checks in the year-end plan. |
| 30 June | Australian financial year-end for most businesses. | Add year-end adjustments, balance sheet reviews and supporting schedules to the June close. |
BAS dates can vary because of eligible extensions, agent arrangements, weekends and public holidays. Confirm the applicable dates for each client using the ATO’s BAS due-date guidance.
For payroll, consult the ATO’s current Payday Super guidance and its information about the Small Business Superannuation Clearing House. The clearing house closed permanently on 1 July 2026, so former users need an alternative arrangement.
The aim is to integrate these obligations into the close calendar without treating every statutory deadline as a month-end reporting deadline.
Australian Compliance Considerations When Outsourcing Accounting Work
Outsourcing accounting activities does not automatically transfer the accounting practice’s professional or regulatory obligations to the service provider. The scope of those obligations depends on the work performed, the engagement and the applicable law and professional standards.
Tax Practitioners Board: Outsourcing and Offshoring
Registered tax agents and BAS agents should review the Tax Practitioners Board’s outsourcing and offshoring guidance, which explains relevant obligations under the Code of Professional Conduct.
In particular, tax practitioners should:
- Obtain appropriate client permission before disclosing client information to a third party, including an offshore provider where relevant.
- Explain who will access the information and where disclosure or storage will occur, as applicable.
- Ensure outsourced tax agent or BAS services are provided competently.
- Maintain adequate supervision and control over work performed by unregistered third parties.
- Review professional indemnity insurance to assess whether outsourced services are appropriately covered.a
- Establish appropriate confidentiality, security and recordkeeping arrangements.
The TPB’s Guidance Statement TPB(GS) 31/2018, updated in April 2026, provides further detail. A signed engagement letter or other appropriate client communication may be used to document permission, but the firm’s arrangements should reflect the actual service and disclosure involved. A generic reference to third parties may not adequately explain the arrangement in every circumstance.
APES 110, APES GN 30, APES 320 and APES 325
Australian accounting practices should consider the professional standards and guidance relevant to their services and membership obligations.
- APES 110 — Code of Ethics for Professional Accountants: Addresses fundamental ethical principles, including integrity, objectivity, professional competence and due care, confidentiality, and professional behaviour.
- APES GN 30 — Outsourced Services: Provides guidance on outsourcing risks, service agreement terms and performance monitoring.
- APES 320 — Quality Management for Firms that provide Non-Assurance Services: Addresses the quality management system for firms providing non-assurance services.
- APES 325 — Risk Management for Firms: Covers establishing, maintaining, monitoring and documenting a risk management framework.
These pronouncements have different scopes and application requirements. Firms should assess which provisions apply to their practice rather than assuming every standard applies identically to every outsourcing engagement.
Privacy, Overseas Disclosure and Data Security
The Privacy Act 1988 and Australian Privacy Principles may apply, depending on the organisation and circumstances. Where the Australian Privacy Principles apply, APP 8 addresses cross-border disclosure of personal information, and APP 11 addresses reasonable steps to protect personal information from misuse, interference, loss and unauthorised access, modification or disclosure.
Firms should also assess applicable Notifiable Data Breaches obligations and incident-response procedures.
Practical safeguards include:
- Role-based access and least-privilege permissions.
- Multi-factor authentication where supported.
- Approved systems for document transfer and storage.
- Confidentiality clauses and appropriate contractual protections.
- Clear rules for offshore access and subcontracting.
- Incident reporting and escalation procedures.
- Regular access reviews and prompt removal of former workers.
- Documented retention, return and deletion arrangements.
Read the OAIC’s Australian Privacy Principles guidance, including the sections on overseas disclosure and information security.
Firms should document their assessment and obtain suitable legal or privacy advice where the arrangement presents material uncertainty.
In-House Accounting vs Outsourced Accounting Support
A hybrid model is often the most practical option for accounting practices that need additional capacity without delegating every responsibility.
| Consideration | In-house team | Outsourced support |
| Routine processing | Uses existing internal capacity | Adds capacity for agreed repeatable work |
| Professional judgement | Retained by appropriately qualified and authorised personnel | Supports decisions with schedules and documented exceptions |
| Workload peaks | May require overtime or recruitment | Can provide additional capacity under an agreed service model |
| Client and compliance responsibilities | Managed within the practice | Must remain clearly allocated to the practice where applicable |
The business case should consider more than the provider’s fee. Include onboarding, internal coordination, software access, review time, rework and transition costs.
For example, if outsourcing saves 12 hours of processing but creates 3 additional hours of review and coordination, the net time released is 9 hours. This is an illustrative calculation, not an Aone performance claim.
A Practical 30-Day Plan to Reduce Month-End Close Delays
A limited pilot allows a firm to test its processes and outsourced support before expanding the arrangement.
| Period | Action | Expected outcome |
| Week 1 | Review the last three closes and document the main bottlenecks. | Baseline performance and prioritised tasks. |
| Week 2 | Standardise the close checklist, document requests and handover process. | Clear responsibilities and consistent workpapers. |
| Week 3 | Onboard the outsourced team for selected tasks and test permissions and access controls. | Defined workflow and controlled information access. |
| Week 4 | Run a close pilot, review exceptions and compare results with the baseline. | Evidence for refining or expanding the arrangement. |
Choose straightforward clients with reasonably consistent records. Avoid starting with engagements that have unresolved accounting issues or unusually complex reporting requirements.
Sample Close Pilot Scorecard
Record these measures before and after the pilot:
| Measure | Baseline | Pilot result |
| Business days to complete the close | Record actual result | Record actual result |
| Required reconciliations completed by day 5 | Record percentage | Record percentage |
| Client documents received after the deadline | Record count | Record count |
| Internal review and rework hours | Record hours | Record hours |
| Total cost per close | Calculate actual cost | Calculate actual cost |
Do not publish performance improvements until they have been measured and validated. A credible case study should specify the period, client type, scope of work and calculation method, with appropriate client consent and anonymisation.
Which KPIs Should Australian Accounting Firms Track?
Focus on measures that explain why the close is late rather than creating a large dashboard of general quality indicators.
- Days to close: Business days between period-end and completion of the agreed reporting deliverables.
- Reconciliations completed by day 5: Percentage of required reconciliations completed by the target date.
- Late client documents: Number of required documents received after the agreed deadline.
- Open close-critical exceptions: Unresolved issues preventing completion or approval.
- Internal review and rework hours: Time spent reviewing outsourced work and correcting avoidable errors.
- Cost per close: Total relevant preparation, coordination, review and provider costs divided by the number of completed closes.
Establish a baseline before setting targets. An eight-business-day close may be a useful internal planning target for a straightforward engagement with timely records, but it is not a universal industry benchmark.
For broader outsourcing quality controls, refer readers to the separate Quality Control in Outsourcing Accounting article. This page should remain focused on the causes, workflow and measurement of month-end close delays.
How to Choose an Outsourced Accounting Partner
Assess a prospective provider against five practical requirements:
- Australian accounting experience: Familiarity with the firm’s accounting platforms, bookkeeping processes and relevant Australian requirements.
- Defined scope and service levels: Written deliverables, turnaround times, exclusions, escalation procedures and handover expectations.
- Appropriate supervision and workpaper quality: Evidence that staff can follow documented procedures and produce review-ready deliverables.
- Confidentiality and security: Suitable access controls, client permission processes, subcontracting transparency and incident response.
- Transparent costs and continuity: Clear fees, onboarding costs, capacity arrangements and procedures for returning records or transferring work.
Before committing to a large portfolio, request a sample workpaper, review the proposed workflow and run a limited pilot.
For additional guidance on quality assurance, link to the firm’s dedicated Quality Control in Outsourcing Accounting article rather than repeating its full framework here.
Common Mistakes to Avoid
Three mistakes are particularly damaging to a month-end close:
- Delegating before fixing the workflow: Unclear instructions simply move existing inefficiencies to another team.
- Leaving client dependencies unresolved: Processing cannot be completed reliably when essential records, explanations or approvals remain outstanding.
- Measuring speed without considering review effort: A faster initial draft does not represent a better close if errors, exceptions or internal review hours increase.
The goal is a predictable close process with fewer avoidable delays, not simply moving tasks outside the practice.
Build a More Predictable Month-End Close
Australian CPA firms can reduce month-end close delays by combining continuous bookkeeping, standardised checklists, timely document collection, clear task ownership and outsourced support for suitable accounting activities.
The most effective approach starts with the firm’s actual bottlenecks. Delegate repeatable work, define handover and review responsibilities, account for BAS and payroll deadlines, and measure results through close times, reconciliation completion, rework and total cost.
For firms considering offshore support, client permission, professional competence, confidentiality, appropriate supervision and controlled data access must form part of the operating model from the beginning.
Need help reducing month-end close delays? Partner with Aone Outsourcing Australia for reliable bookkeeping and reconciliation support that fits your firm’s workflow.
Contact us to discuss your requirements.
Frequently Asked Questions
1. How can Australian CPA firms reduce month-end close delays?
Start by reviewing recent close delays, standardising the close checklist, setting client document deadlines and completing routine reconciliations throughout the month. Outsourced accounting support can add capacity for repeatable processing, while the firm’s designated personnel retain appropriate review and decision-making responsibilities.
2. What accounting tasks can be outsourced during month-end close?
Suitable tasks may include transaction categorisation, bank reconciliations, accounts payable and receivable processing, supporting schedules, fixed asset register maintenance and draft workpapers. The agreed scope should reflect staff competence, client permissions, security requirements and the practice’s review procedures.
3. Is outsourced accounting support suitable for small Australian accounting practices?
Yes. Smaller practices may benefit when client workloads fluctuate or internal staff spend substantial time on repetitive bookkeeping. A limited pilot involving straightforward engagements can help establish whether the arrangement reduces backlogs and releases enough internal capacity to justify the total cost.
4. Does outsourcing transfer a CPA firm’s professional responsibilities?
No. Outsourcing does not automatically remove the firm’s applicable professional, contractual or legal obligations. The practice should document the scope of work, client permissions where required, supervision, review, confidentiality and recordkeeping arrangements.
5. How long should a month-end close take?
There is no universal deadline. A firm may use five to eight business days as an illustrative planning target for straightforward engagements with timely source documents, but this is not a universal benchmark. Client complexity, inventory, consolidation, unresolved exceptions and reporting requirements can extend the timetable.
6. How does accounting automation help speed up month-end close?
Automation can reduce manual data entry, apply suitable transaction rules, match transactions and flag exceptions. Staff must still investigate unusual items, validate coding, complete reconciliations and review adjustments before reports are approved.
7. What should firms check before hiring an outsourced accounting provider?
Assess Australian accounting experience, software compatibility, defined service levels, workpaper quality, supervision, client confidentiality, security controls, subcontracting arrangements, transparent pricing and business continuity. A limited pilot provides evidence of the provider’s performance before the firm expands the arrangement.
8. How does Payday Super affect accounting and payroll workflows?
Payday Super commenced on 1 July 2026. Employers generally need to ensure superannuation contributions reach employees’ funds within seven business days after payday, subject to applicable rules and exceptions. Accounting practices supporting payroll should plan for regular reconciliation, accurate employee fund details, payment monitoring and prompt resolution of contribution errors.
9. Do I need client permission to outsource accounting work?
For registered tax and BAS practitioners, the TPB’s Code of Professional Conduct requires client permission before disclosing information about a client’s affairs to a third party, unless a legal duty applies. The firm should explain the proposed arrangement, including who will access the information and where disclosure will occur, as relevant. Review the TPB’s current outsourcing and offshoring guidance before implementing the arrangement.
10. What does the Tax Practitioners Board expect when tax or BAS work is outsourced offshore?
The TPB expects registered practitioners to meet their relevant confidentiality and competency obligations, maintain appropriate supervision and control over outsourced work, and ensure services are provided competently. Practitioners should also assess client permission, security arrangements and professional indemnity insurance. Consult the TPB’s current guidance for the requirements applicable to the specific arrangement.